Late-August Heat Lifts Power Prices
Pricing Signals
Natural-gas production has increased to 109.7 Bcf/d, while LNG exports have risen to 17.9 Bcf/d. Export volumes have not operated at full capacity over the past month or two, though both Freeport LNG and Plaquemines LNG increased activity last week.
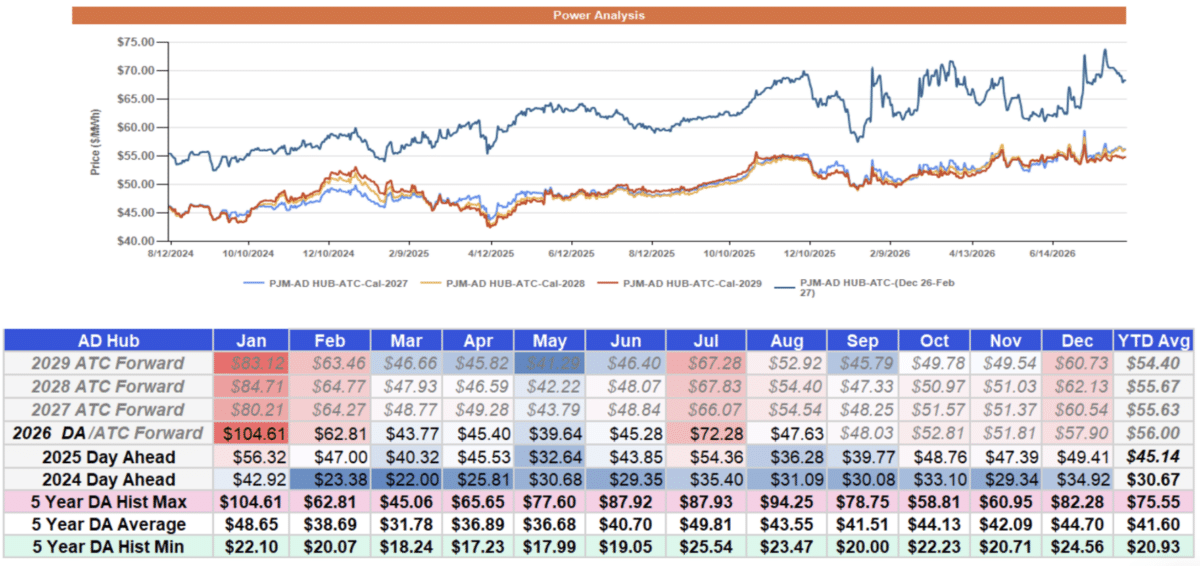
Looking ahead to winter, most months appear favorably priced relative to January, which remains above $80/MW. At this point last year, Winter 2026–2027 pricing traded roughly $3–$5 lower than current levels. However, future shoulder-month pricing is at or below where it traded a year ago.
Natural Gas Storage and Supply
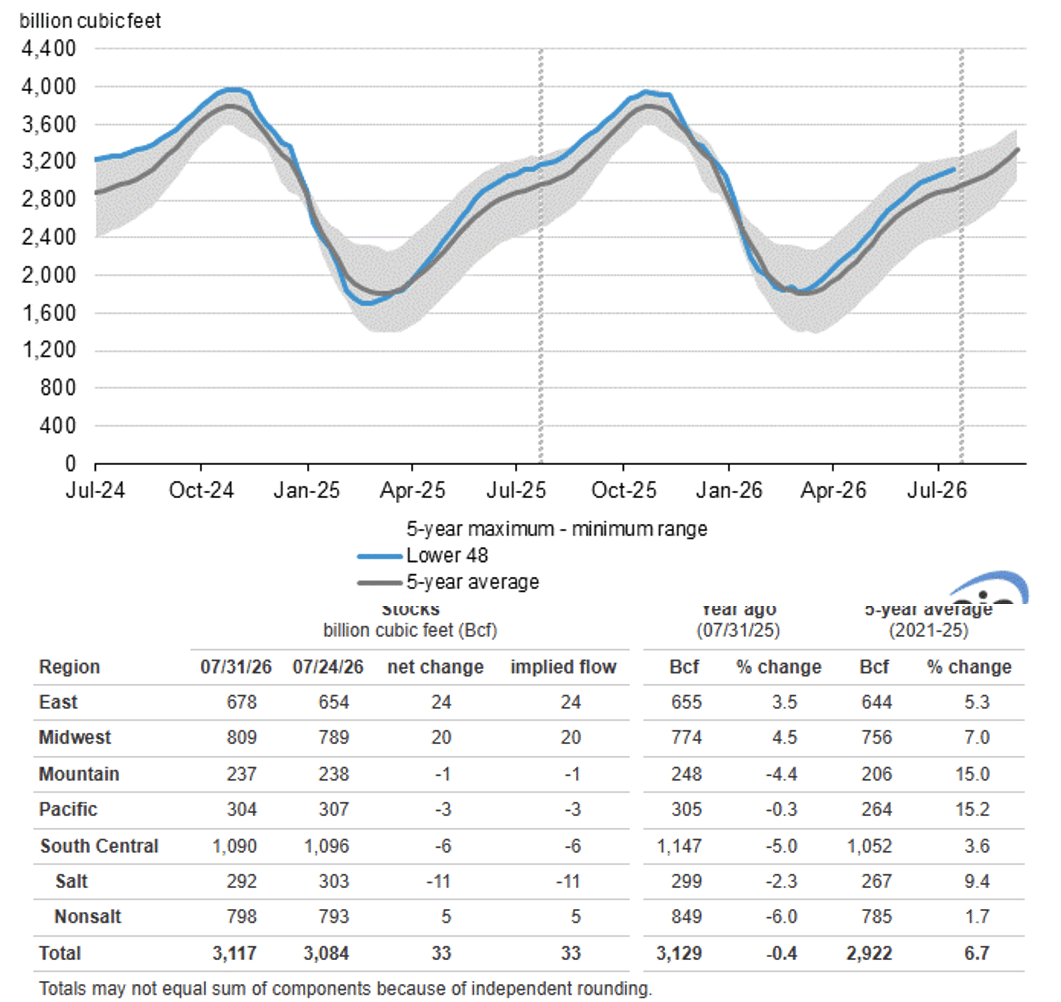
Weekly EIA Natural Gas Storage Report
The weekly EIA Natural Gas Storage Outlook report tracks the volume of natural gas in underground U.S. storage, revealing weekly fluctuations and comparison against 5-year averages.
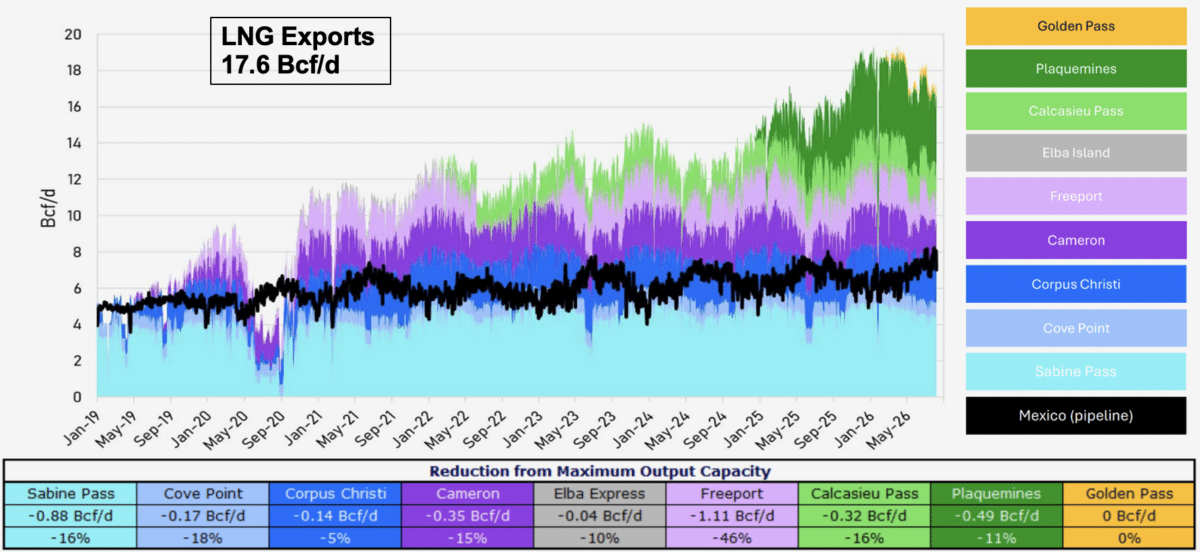
LNG Exports
Both NYMEX forward strips and LNG export levels remain near recent averages, suggesting a largely balanced market for now.
(Charts: NYMEX Natural Gas Calendar Strips and LNG Exports)
What to Do Now
- Watch 2029 shoulder-month opportunities: March through May and September through November are currently priced below $50/MWh.
- Consider hedging December, February, March, and April. Securing 50% of anticipated load in those months at today’s prices may offer a strong balance of cost certainty and flexibility.
- Hold off on January for now. Forecasts point to a potentially strong El Niño winter pattern, which could moderate pricing if temperatures trend milder.
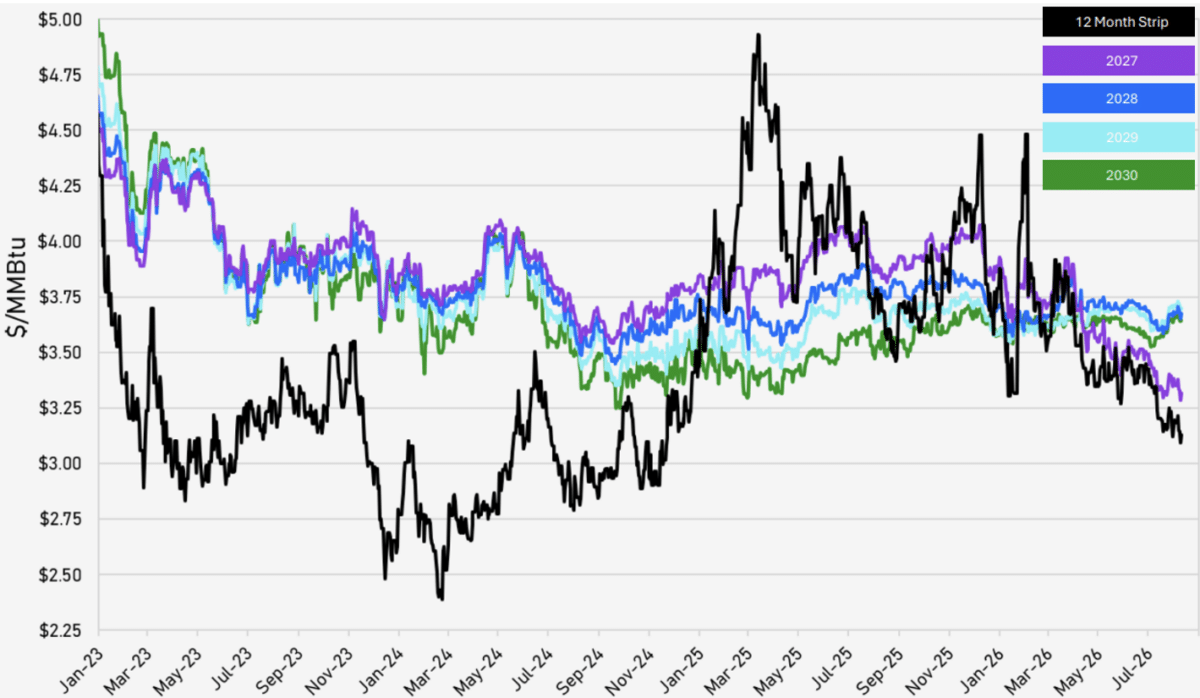
NYMEX Natural Gas Calendar Strips
The NYMEX 12-Month Strip averages the next 12 months of Henry Hub futures into one price. It’s a powerful indicator of market sentiment — allowing traders (and end users) to lock in year-long coverage at a blended rate.
Watching shifts in this strip helps gauge the broader direction of gas markets, beyond just the prompt month.
Natural Gas Production: Lower 48 States
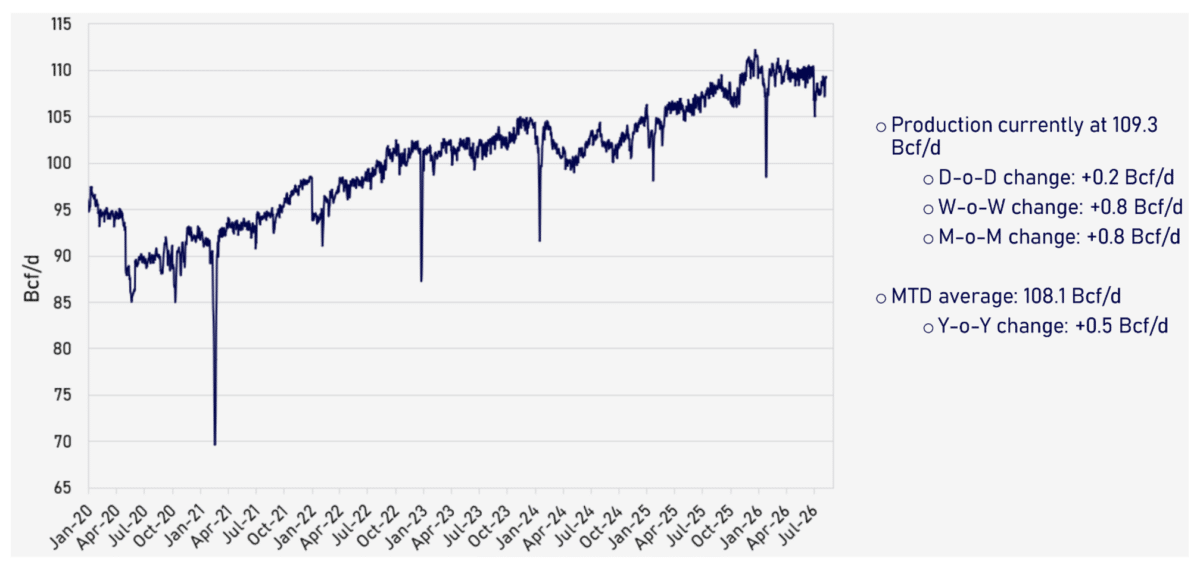
Production Snapshot
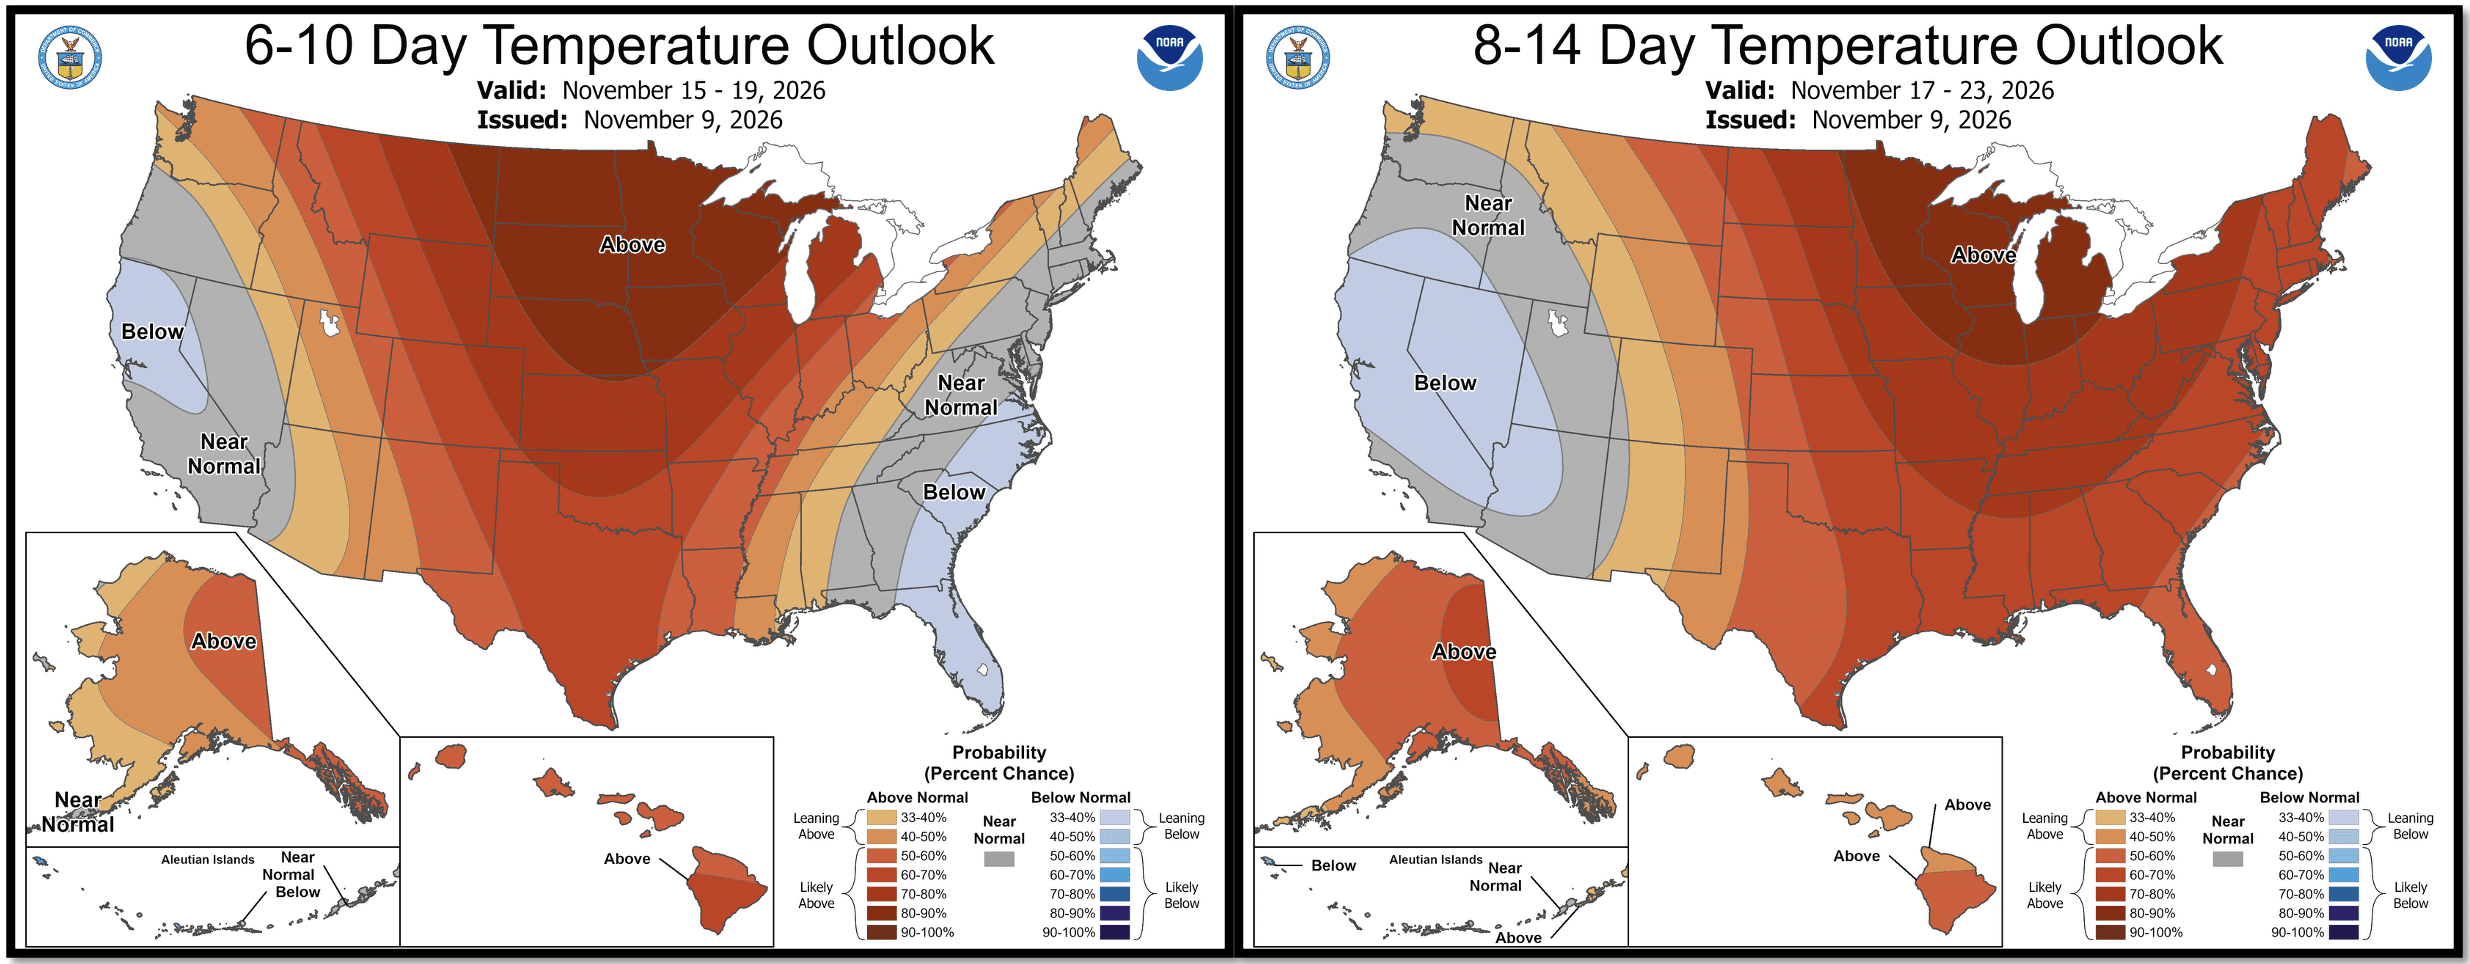
Weather Outlook
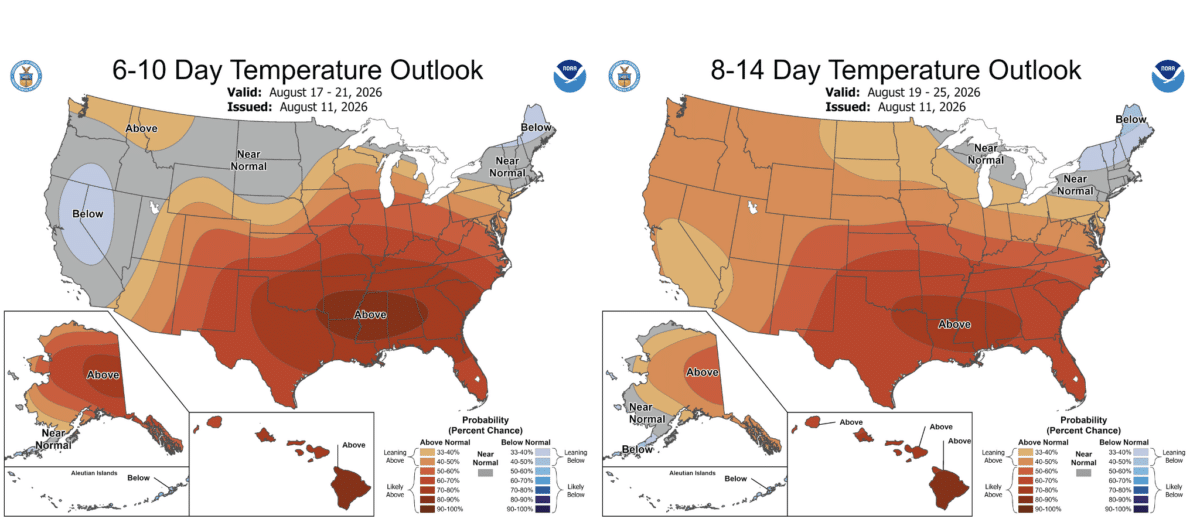
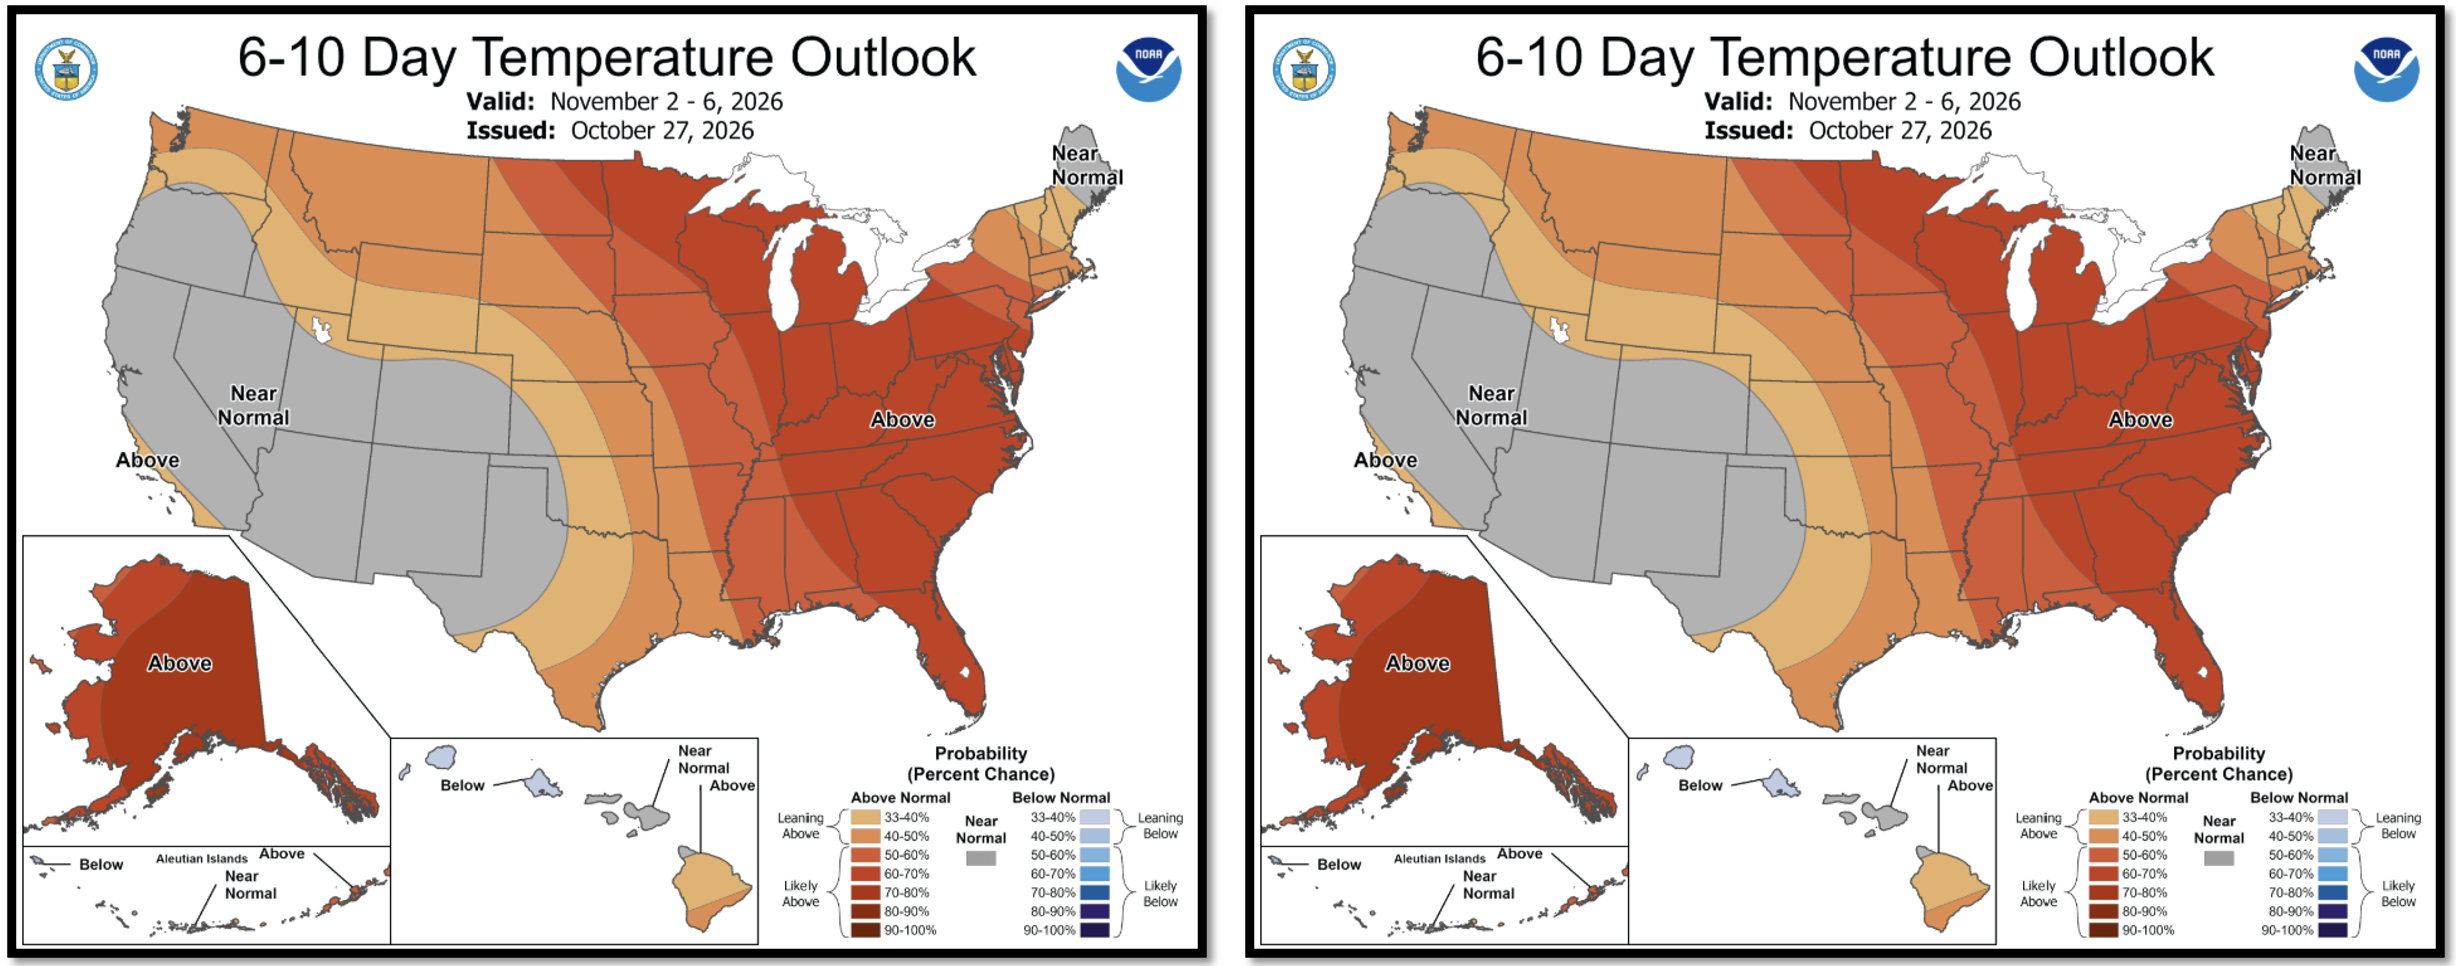
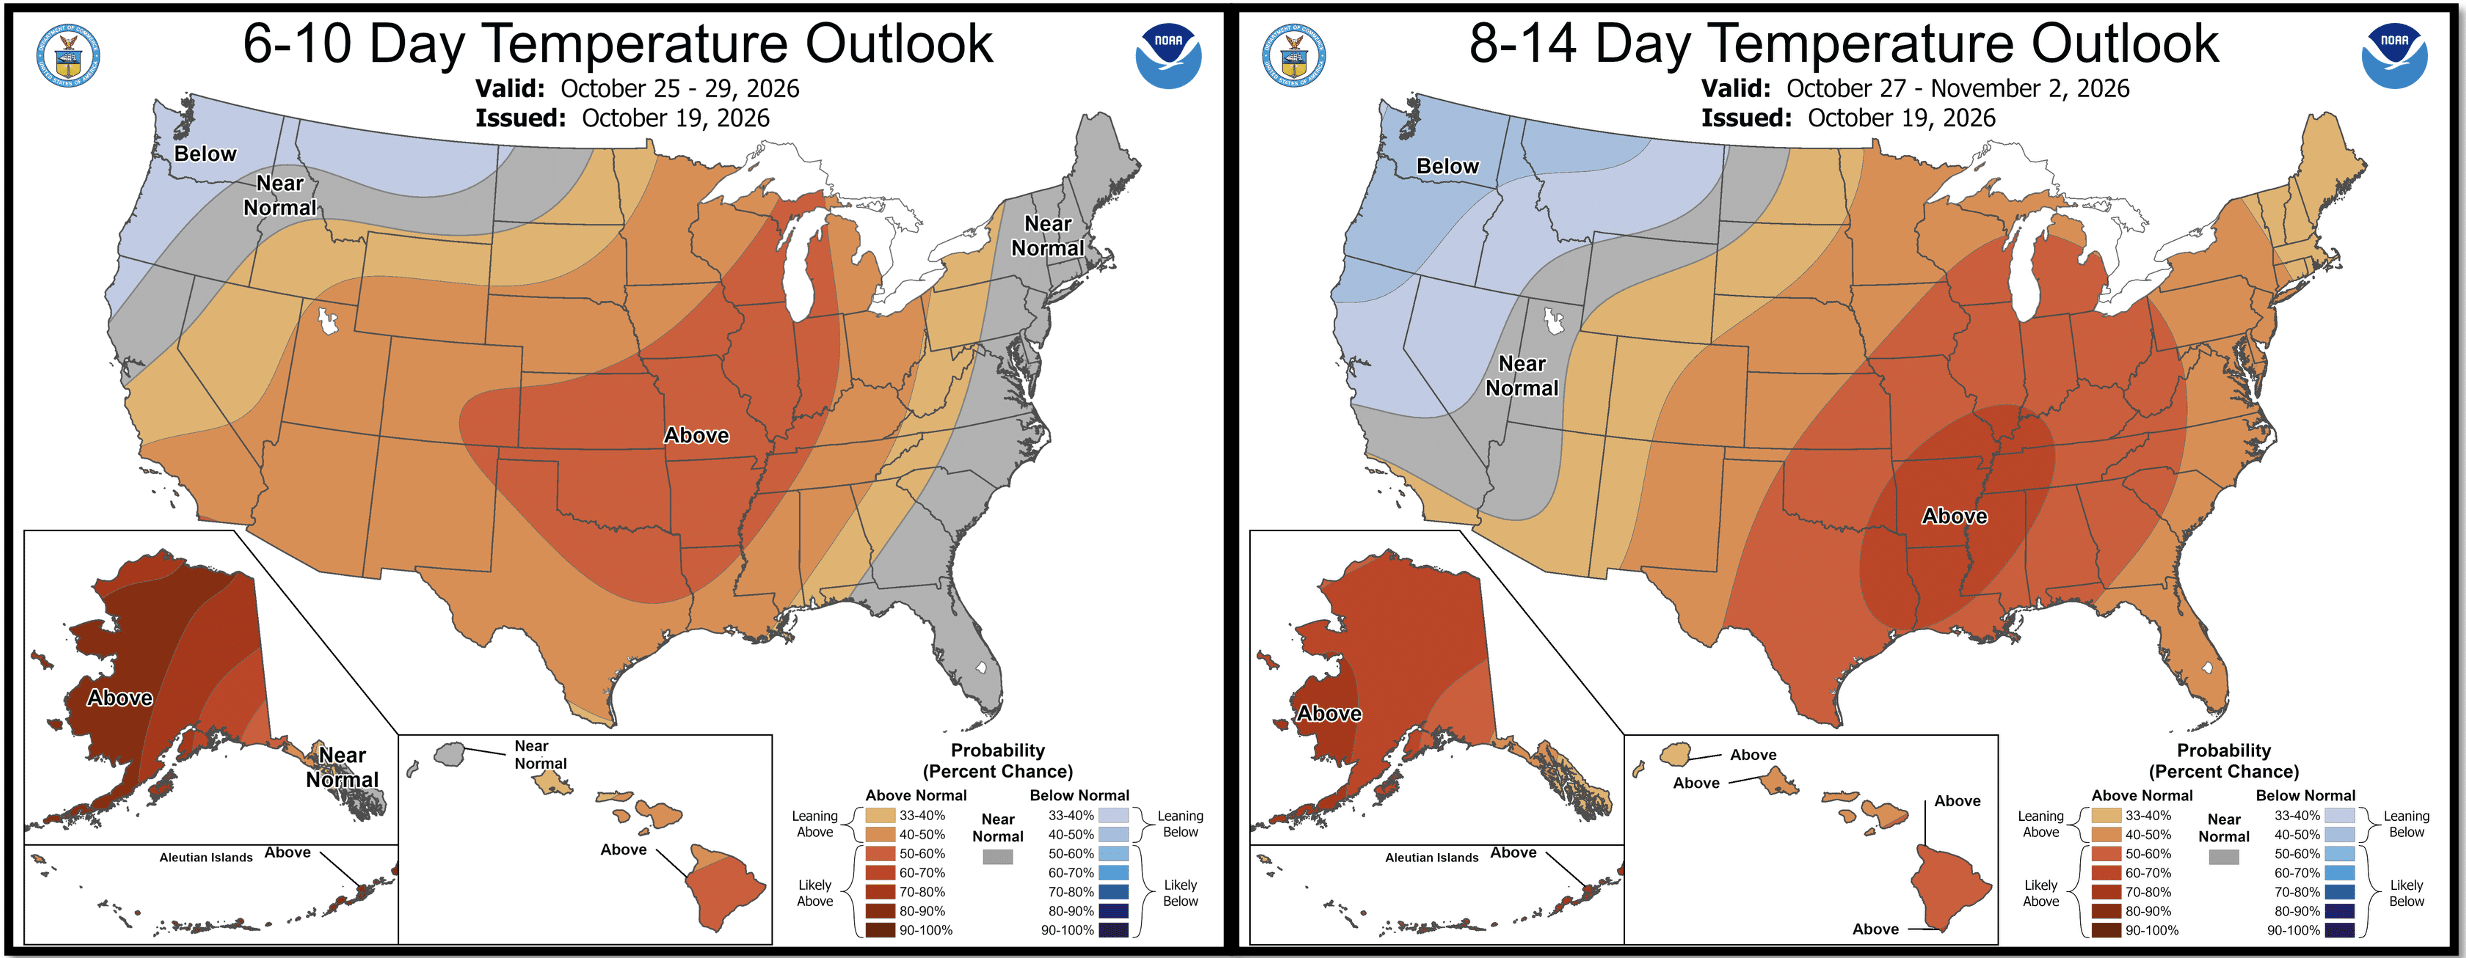
7-Day Weather & Demand Outlook
- The Southwest is expected to experience the most intense heat.
- Texas and much of ERCOT are also projected to see temperatures in the 100s.
- Sustained heat across southern markets will keep cooling demand elevated.
- Northern areas should be seasonable to warm, with highs primarily in the 70s and 80s, although a few locations may still reach the 90s.
PJM Ad Hub DA & Forward Trend Analysis
This chart shows where current PJM AD Hub day‑ahead and forward power prices sit versus the past two years of trading, and whether today’s levels look cheap or expensive for each future period.
Big picture
- Each bar represents a 24‑month trading range for a specific month, quarter, or year in the future, with the light blue band showing the lowest and highest prices over the last 2 years.
- The dark mark inside each bar is today’s forward price, so you can instantly see if the market is currently near the top, middle, or bottom of its recent range.
What the table tells you
- The table underneath lists, for each period (Q2‑2026, Q3‑2026, 2027, 2028, 2029, 2030, etc.):
- Current price in that strip.
- The maximum and minimum prices over the last 24 months and the dates they occurred.
- The current percentile (for example, 3% means today is near the very bottom of the 2‑year range; 86% means it’s near the top).
- The actual prices at the 25th, 50th, and 75th percentiles act like “cheap / mid / rich” reference points.
How to interpret it for decisions
- Periods where the current price is low on the bar and at a low percentile suggest relatively attractive buying or hedging opportunities compared with recent history.
- Periods where the current price is high on the bar and at a high percentile indicate the market is pricing that future strip richly, so you may want to be more cautious about locking in too much volume there.
NYMEX Price Trend Analysis
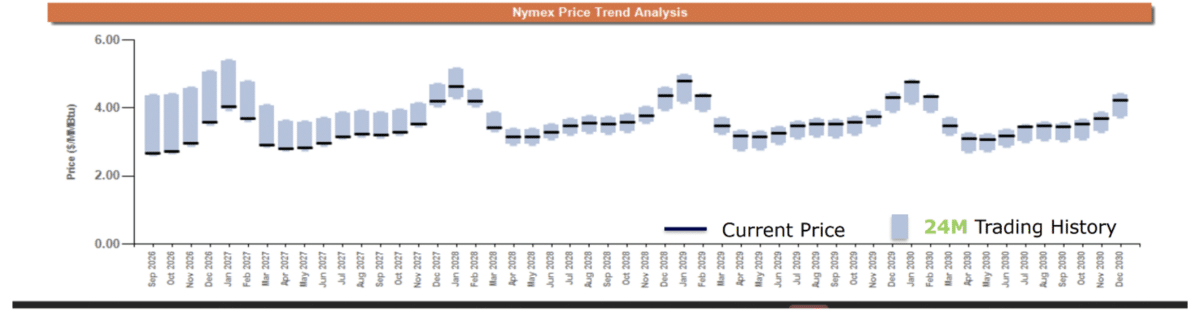
This chart shows that NYMEX natural gas prices over the next several years are relatively low compared with their recent trading range, but they remain volatile and tend to spike in winter months.
What the chart is basically saying
- It is a forward curve: each bar represents what the market today thinks gas will cost in a specific future month, based on NYMEX futures trading.
- The light blue “24M trading history” band around each month shows the range in which that contract has traded over the past two years, and the black line shows today’s price within that range.
- For many future months, today’s price is near the bottom of that 2‑year range (a very low percentile in the table), indicating the market is currently pricing gas on the cheaper side compared with recent history.
Big-picture energy market takeaway
- The curve gently rises over time and bumps up in winter (late 2026, 2027, 2028), reflecting expectations of stronger heating demand in cold months and the typical seasonal risk in natural gas.
- Because today’s prices sit near recent lows for many of those future periods (single‑digit to low‑double‑digit percentiles), the market is not currently forecasting a severe supply crunch; instead, it suggests adequate supply and only moderate risk premiums built in.
- For a business buyer, the practical implication is: forward prices are historically attractive right now, especially if you want to lock in budget certainty through the next several winters rather than gamble on future spikes.